
The average property price in England reached around £293,000 in July 2026
For generations, owning a home has been an important financial milestone for many British Asian families.
However, rising property prices, mortgage costs and everyday expenses are changing how achievable that ambition feels for younger buyers.
Government figures show that 56% of Asian households in England owned their home in the two years to March 2023.
For younger British Asians, saving for a deposit while managing rent and household costs can make entering the property market particularly challenging.
The traditional dream of owning a home remains strong, but the route towards achieving it is changing.
A Changing Homeownership Dream
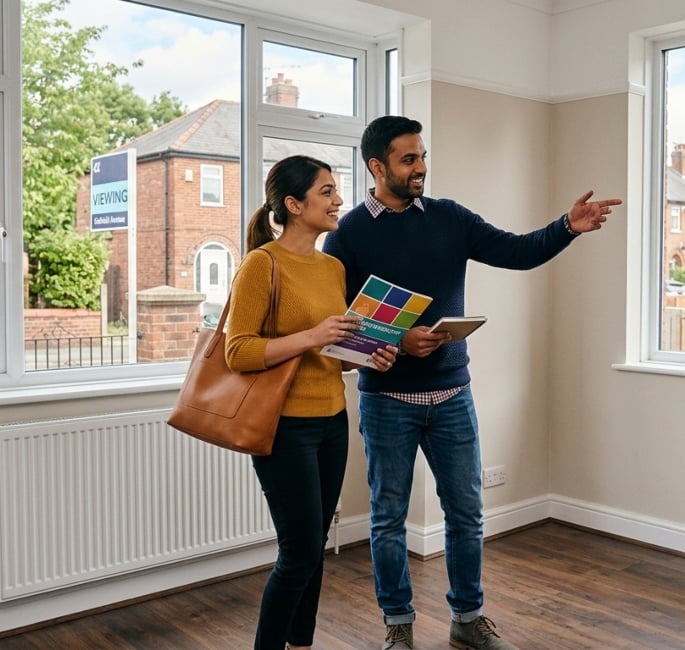
For many British Asian families, owning a property represents more than having somewhere to live.
It can mean financial security, independence and creating something that can eventually be passed down to the next generation.
Previous generations also often viewed buying a home as an important part of establishing their families in Britain.
However, younger adults are entering the property market under very different financial conditions.
High rents can make it difficult to build savings, while mortgage affordability checks can limit what buyers are able to borrow.
The English Housing Survey 2024-25 found that 42% of households aged 16 to 34 were owner-occupiers. A further 43% were private renters.
Despite this, homeownership remains an ambition for many younger people.
The survey found that 69% of people aged 16 to 34 expected to buy a home eventually.
For younger British Asians, the question is increasingly whether they can afford to reach that milestone, rather than whether they want it.
Different Communities, Different Experiences
There is no single British Asian experience when it comes to buying a home.
Official ethnicity and housing figures show considerable differences between Asian communities.
Indian households had a homeownership rate of 68% in the latest available data, while the figure was 55% among Pakistani households.
Among Bangladeshi households, the rate was lower at 37%.
These differences can reflect factors including household income, age, location and family circumstances.
Older homeowners have also had more time to save and benefit from changes in property values.
Younger buyers are facing a very different market.
Family support can make a significant difference, particularly when parents are able to help with deposits or allow their children to remain at home while saving.
But this is not an option available to every household.
The ability to rely on family wealth can therefore shape who is able to get onto the property ladder and when.
House Prices Are Raising the Barrier
Property prices remain one of the biggest obstacles for first-time buyers.
The average property price in England reached around £293,000 in July 2026, according to the latest UK House Price Index.
Although prices are not rising as quickly as during previous periods, the cost of buying remains significant for households trying to save a deposit.
For renters, the problem can become circular.
A large proportion of monthly income can go towards rent, leaving less available for savings.
The longer it takes to build a deposit, the longer a prospective buyer may remain in the rental market.
For some British Asian households, other financial commitments can add another layer of pressure.
Family contributions and weddings can all affect how much someone can put aside.
This does not apply to every family, but it highlights why housing affordability cannot be separated from wider household finances.
Buying a home is rarely an isolated financial decision.
It can involve balancing personal savings with expectations around family, location and long-term security.
Mortgage Costs Add Another Pressure
Having a deposit does not automatically make homeownership affordable.
Buyers must also demonstrate that they can manage their mortgage repayments, with interest rates affecting how much they can borrow.
Higher borrowing costs can push buyers towards smaller properties or cheaper areas.
Location can be particularly important for younger British Asians.
Many people want to remain close to parents, relatives, established communities, places of worship and South Asian businesses.
Moving somewhere cheaper may therefore involve moving further away from the support networks that have shaped their lives.
That can make the decision more complicated than simply choosing the lowest-priced property.
The age at which people buy is also changing.
Younger buyers are increasingly taking longer to reach the point where purchasing a property becomes financially realistic.
For British Asian families, this can create a gap between traditional expectations and the realities facing younger generations.
The idea of buying a home by a certain age may remain familiar, but the financial conditions required to achieve it have changed.
Is the Dream Disappearing?
The evidence suggests that the British Asian homeownership dream is changing rather than disappearing.
Younger people continue to see owning a home as an important long-term goal, despite the financial barriers surrounding the housing market.
Recent housing data also shows that ethnic minority households continue to enter the property market.
However, getting onto the ladder can depend heavily on savings, household income and access to family support.
For some British Asians, staying with parents for longer may provide an opportunity to save.
For others, buying may require moving further from family, choosing a smaller property or waiting until later in life.
The dream of owning a home has not disappeared.
Instead, it is becoming a longer-term goal that may require more financial planning and compromise.
For British Asian families, that could gradually change expectations around when someone should become a homeowner.
The question is no longer simply whether the next generation wants to own property.
It is whether Britain’s housing market will make that ambition realistically achievable.